Protection
Insurance starts with what would need to continue.
The people and the plans already in motion. The mornings, the people and the plans already in motion. Protection is what keeps them steady.
One household picture
What a decision is actually made around.
People, income and obligations are not three separate products. They belong to one household, and each part carries the others.
Life changes first. The terminology comes later.
- Building a life together
- Someone depends on you now
- A home carries commitments
- Income supports more than yourself
- Looking further ahead
- People
- People whose circumstances depend on income they do not earn themselves.
- Income
- The income the household is built around — the span everything else attaches to.
- Obligations
- Commitments of different sizes and lengths that continue whether or not circumstances change.
Life insurance, in plain English
Money for the commitments that keep going.
Life insurance is a contract with an insurer. You pay premiums to keep coverage in force.
If the insured person dies and the claim is payable under the policy, the insurer pays a death benefit to the named beneficiary or estate.
The policy isn’t the point.
What the money can help keep possible is.
How the benefit works
- Coverage in force
- Payable claim
- Death benefit
- Financial choice
When a death benefit is payable, it can provide liquidity to the beneficiary or estate.
What can the money help do?
- Keep life moving
- Help replace some of the income a household relied on.
- Clear obligations
- Help pay a mortgage, loans or other debts.
- Cover final and estate costs
- Help with funeral and final expenses, and tax or estate obligations that may arise.
- Preserve choices
- Create liquidity so important decisions are not forced by an immediate need for cash.
- Leave something behind
- Create or strengthen a legacy for family, other beneficiaries or a charity.
Two broad ways life insurance can work.
Term
Coverage for a defined period.
Often used where the need has a foreseeable end. Term insurance normally does not build cash value.
Permanent
Coverage designed to last for life while the policy remains in force according to its terms.
Permanent insurance generally builds cash value. Whole Life and Universal Life are common forms.
Participating whole life
Some participating whole-life policies may receive policyholder dividends. Dividends are not guaranteed.
Depending on the policy, dividends may be used in different ways, including increasing coverage or reducing premiums.
Permanent coverage may also be relevant to certain long-term estate, legacy or broader wealth objectives.
Protection comes first. Costs, guarantees, policy values, access to those values, tax treatment and suitability depend on the contract and the person’s circumstances.
Start with the need, not the product.
Different risks call for different kinds of protection.
Types of insurance
Coverage is not one thing.
Clearstone does not recommend a product from a web page. Which structure fits is a conversation, informed by your circumstances.
- Life Insurance
Provides a death benefit when an insured person dies while coverage is in force, helping provide financial support to beneficiaries or the estate.
Whole LifeUniversal LifeTerm Life - Critical Illness Insurance
May provide a lump-sum benefit after diagnosis of a covered serious illness when the policy’s requirements are met.
- Disability Insurance
Can replace part of your income when an illness or injury prevents you from working, subject to the policy’s terms.
- Health and Dental Insurance
Can help with eligible health, prescription, dental and related expenses that may not be fully covered elsewhere.
- Mortgage Life Insurance
Life coverage focused on the financial impact of a mortgage, helping provide funds that can be used toward housing obligations after death.
- Travel Insurance
Can help cover specified emergency medical and travel-related costs that arise while you are away from home.
- Visitor Insurance
Can help cover eligible emergency medical expenses for visitors to Canada who may not be covered by a provincial health plan.
for visiting newcomers or foreign nationals
- Final Expense Insurance
Life insurance designed to provide a death benefit that can help with funeral and other final expenses.
- Long Term Care Insurance
Can provide benefits toward eligible care costs when the insured meets the policy’s requirements for ongoing assistance or care.
Understanding the need and the type of coverage is only part of the decision.
The insurer still decides whether coverage can be offered and on what terms.
Application · Underwriting
You provide information. The insurer decides.
The forward line ends at the insurer’s decision. Anything after it is conditional, and nothing before it makes it certain.
- Your circumstances become the information an application asks for.
- The application is submitted to the insurer.
- Underwriting is the insurer’s own review of that information. The decision is theirs.
- Policy terms exist only if the insurer offers them, and are set by the contract that follows.
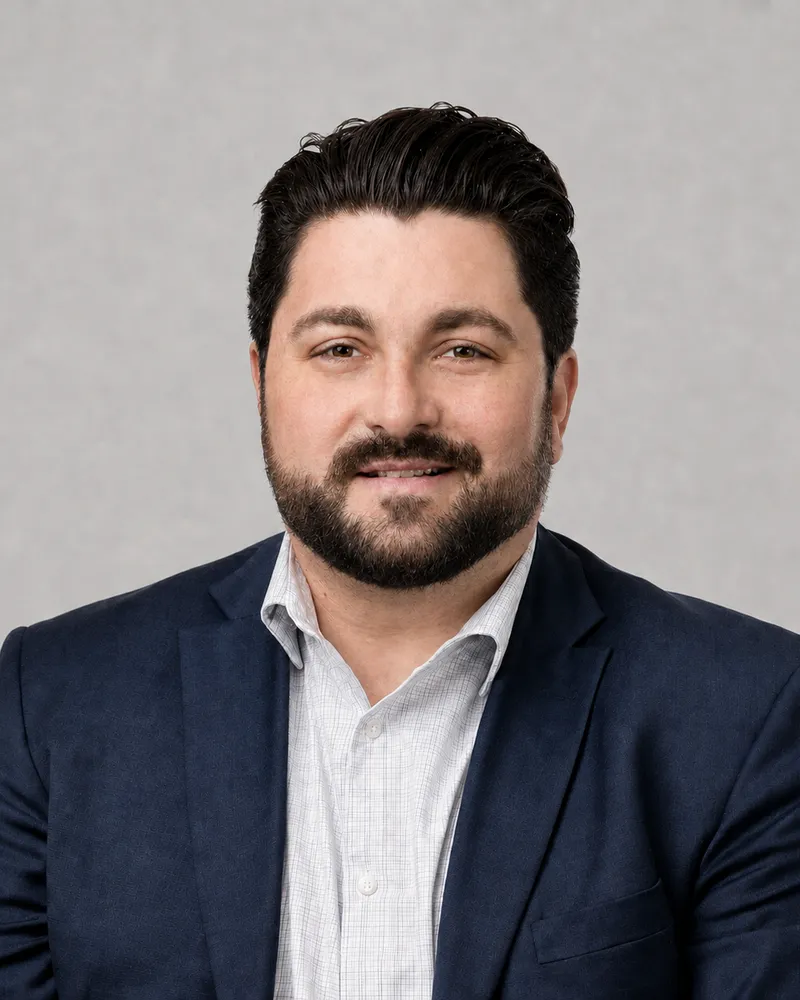
Human guidance
Explore it digitally. Talk it through when it gets personal.
Clearstone can help you clarify what you are protecting, explain what each choice involves, and support you through the application.
Nicholas Gaudet
Founder & CEO, Clearstone Financial
The relationship
Where Clearstone fits.
Clearstone prepares and presents the application. The insurer underwrites it and decides.
You
Your circumstances, and the information the application asks for.
Clearstone
Prepares the application, presents it, and explains what is being asked and why.
Clearstone does not underwrite and does not make the insurer’s decision.
Distribution relationship
Insurance products are distributed through IDC Worldsource Insurance Network Inc.
Insurance carriers
Protect the life you’re building.
Start with the people and the plans. The product comes later.