Buying a home.
First home or the next one, the starting point is the same: understanding what the application actually supports before anything is submitted.
Mortgages
Understand the file, compare the lender directions actually available to it, and move with a clear next step.
Mortgage brokering through 
Where mortgages start
These are the contexts a mortgage conversation usually starts from. Which of them leads where depends on the file, the property and the lender.
First home or the next one, the starting point is the same: understanding what the application actually supports before anything is submitted.
A maturing mortgage is a decision point, not a form to sign. Staying with the current lender and moving to a different one are both real options.
Refinancing changes the amount, the structure or the purpose of an existing mortgage. Whether it makes sense depends entirely on the file.
Arriving in a new country and buying a home at the same time means learning an unfamiliar lending system while everything else is also unfamiliar.
Residential income property is read differently from a home you live in, and the file carries more moving parts than one address.
Financing a build follows the construction itself rather than arriving at one closing date, so the timing sits at the centre of the conversation.
A recreational property is assessed on its own terms — where it is, how it is reached, and how it is actually used through the year.
A parcel with nothing built on it is a different kind of file from a finished property, and it is worth understanding that before you commit.
Financing a commercial property follows the property and the use it is put to, rather than the policy that governs a home you live in.
Some homeowners want to understand what a long-held property can do for them without selling it, and what that would mean over time.
An offset structure treats everyday balances and the mortgage as related quantities rather than keeping them in separate places.
Mortgage balance Linked savings balance
A readvanceable mortgage is a structure certain long-term strategies depend on, including the Smith Manoeuvre™.
Mortgage portion Linked credit portion One property
Before considering it:
Smith Manoeuvre™ is a trademark used under licence through SMCG.
Why a broker
Both are real routes to a mortgage. The difference is how wide the comparison is before you commit to one.
You are working with an advisor from that bank. The mortgage directions they can offer come from that institution.
Your file
One institution
That institution’s available mortgage directions
That may well be the right solution — but on its own it does not tell you how that mortgage compares with other lender directions available to your file.
Your broker is not limited to one bank’s product shelf. One prepared mortgage file can be used to compare multiple lender directions available through the brokerage.
One prepared file
Available lender field
Depending on your file, those directions may include:
Not every category is available on every file. Availability depends on the file, lender criteria, geography, the property and brokerage access.
Compare
One selected submission
The job is to compare those available directions with your goals in mind, then help you choose where the file should go.
A mortgage decision includes more than a headline rate. Rate sits inside cost, one of these four — the lowest displayed rate and the strongest overall mortgage are not automatically the same mortgage.
Instead of choosing from one institution’s product shelf, you can compare multiple available lender directions before deciding where your file should go.
When you deal with one institution alone, you are comparing within that institution. A broker widens the comparison before you choose. The broader the relevant comparison, the better informed the decision can be.
Mortgage brokering through Vine Mortgage.
Clearstone Financial is not a lender, and neither is Vine Mortgage. The brokerage prepares and submits the file; a separate lending institution assesses it and decides.
Why Clearstone
Two named people stay accountable for the relationship and the file.
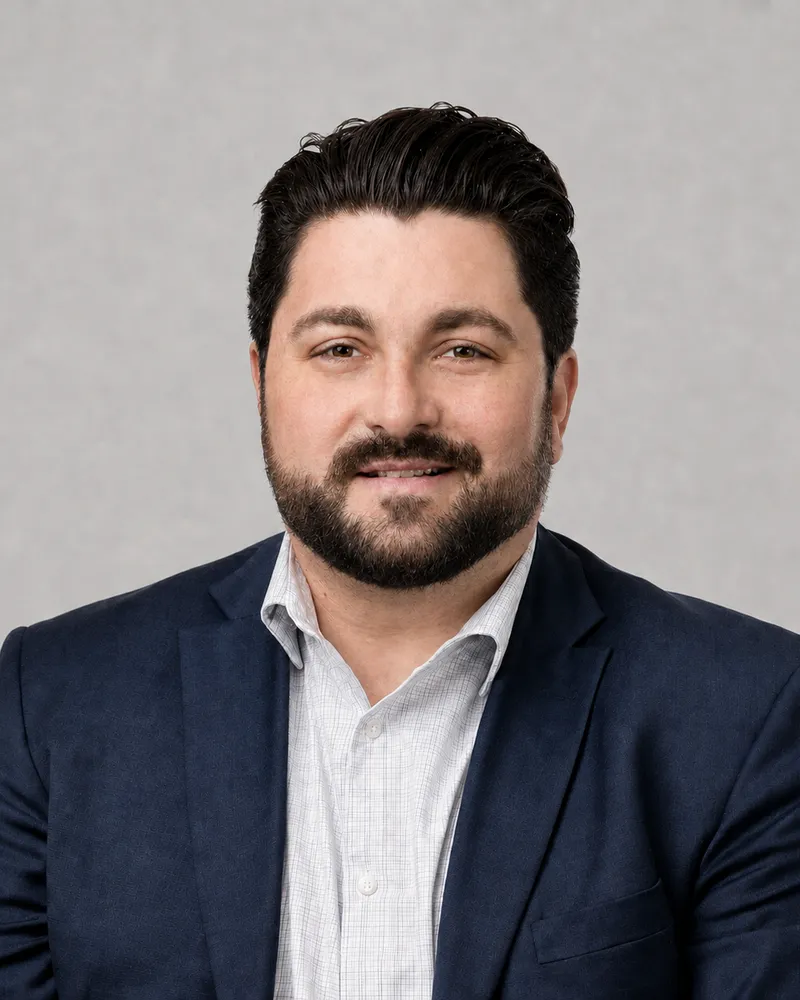
Founder & CEO
Nicholas oversees the whole Clearstone financial picture. A mortgage sits inside that picture rather than beside it, and he stays accountable for the relationship as the file moves.
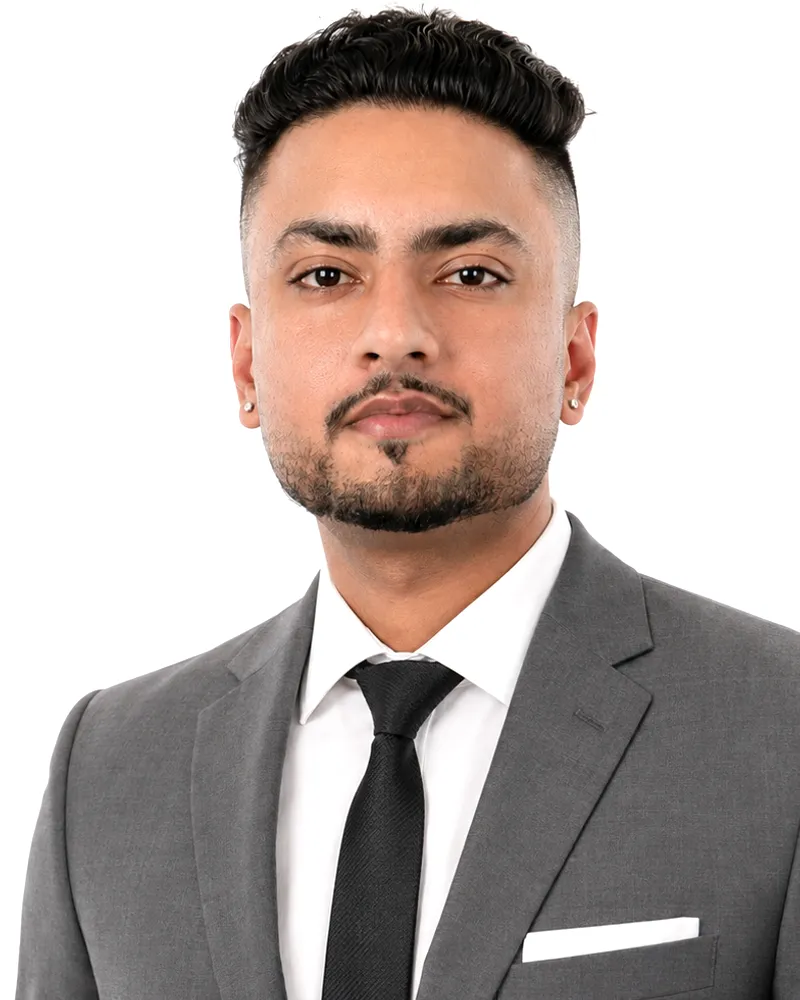
Director, Mortgage Operations
Anmol leads Mortgage Operations: intake, file preparation, the fulfilment workflow, and coordinating the file’s progress with lenders and with you.
Specialist functions support file preparation and fulfilment. None of them makes the lender’s decision.
How the file moves
A mortgage is not one decision made once. This is the order the work happens in, and who is responsible at each point.
Brokerage side
Start from what you are trying to accomplish, and by when. The direction follows the objective, not a product.
You and Clearstone
Collect the application and the evidence behind it. Documents substantiate what the application represents; they are not a guarantee.
You and Clearstone
Broker-side review for completeness and consistency, so known issues surface here rather than after a lender has seen them.
Clearstone and Vine Mortgage
With the file understood, discuss the lender directions actually feasible for it, and what each one trades away.
Clearstone and Vine Mortgage, with you
You settle on the direction to pursue, with the trade-offs understood before anything leaves the office.
Weighed against each other — then you choose one.
You decide
The prepared file goes to the chosen lender. From here the lender assesses it and makes its own credit decision.
Submitted by the brokerage — the lender decides
A commitment usually carries conditions. We coordinate them; the lender and insurer decide whether they are met.
Clearstone coordinates — the lender and insurer decide
You, the lender and the legal professionals complete the final steps, working to one date and one set of documents.
Lawyer or notary closes — the lender advances funds
Where a mortgage can sit
Not every mortgage is assessed the same way. These are the three broad pathways, and the question each one actually turns on.
Traditional lending
The key question Does the file fit conventional policy?
Outside standard policy
The key question What needs flexibility, and what is the longer-term plan?
Short-term and equity-supported
The key question What is the realistic exit plan?
Which pathway suits a file is a question about the file, not a ranking. None of these is a better or worse kind of borrower.
After funding
Funding isn’t the end of the Clearstone relationship. The mortgage can stay under review for the whole of its term — your estimated equity position, and whether changing conditions create something worth looking at again.
Every Clearstone mortgage client is offered one — a look at how the mortgage sits alongside the rest of your picture.
It is optional. It is not a condition of getting a mortgage, of keeping one, or of using any other Clearstone service.
Decide
A change in rates or mortgage options may create an opportunity worth considering. Whether it is worth acting on depends on the file — a lower advertised rate does not by itself produce a saving.
If borrowing costs can be reduced, maintaining the same payment may allow more of each payment to reduce principal and shorten the remaining amortization.
A lower advertised rate does not automatically mean changing mortgages makes sense. Penalties, fees, qualification, remaining term, mortgage structure and other considerations can make staying put the better decision.
Measure
Estimated property value
Estimated equity position
Re-measured at each review
Mortgage position
Review
Equity and interest-rate reviews may be available at one of these intervals, set to suit how closely you want to follow the mortgage.
Estimated property values used in Clearstone equity reports may be informed by aggregated third-party market data, together with the mortgage information available at the time of the review, to give an ongoing estimate of your home-equity position.
Get started
Tell us what you are trying to accomplish and which of these situations you are actually in. We will start from there.
Clearstone uses essential technology to run this site. Your privacy choices here control certain optional site technologies. Some embedded and platform services can load independently of these choices; our Privacy Policy explains them. You can change your choices at any time. See our Privacy Policy.