Advanced Strategies
The Smith Manoeuvre™
Your mortgage and your long-term investments may not need to happen one after the other.
Part of every mortgage payment reduces principal. Under a compatible structure, that repaid room may be borrowed separately and invested for the future — a second objective, running alongside the first.
Borrowing to invest can magnify gains and losses. Suitability and tax treatment depend on individual circumstances.
What is the Smith Manoeuvre™?
The mortgage is the structure. The investment borrowing is a separate decision.
The Smith Manoeuvre™ is a strategy for homeowners that uses a compatible readvanceable mortgage to create a separate source of borrowing for investment while the regular mortgage continues to be paid.
As mortgage principal is repaid, additional borrowing room may become available under the mortgage and lender’s product terms. An agreed amount may then be borrowed separately and directed to eligible non-registered investments.
Where the applicable tax requirements are met, interest on qualifying investment borrowing may be deductible.
Because the strategy uses borrowed money to invest, it introduces leverage and additional risk. Suitability and tax treatment depend on individual circumstances.
The basic idea.
One payment you already make. A second objective it may make room for.
A regular mortgage payment reduces principal. Principal repayment may make additional borrowing room available under the mortgage and product terms. Available room is not the same as borrowing: nothing is owed until a separate decision is made to borrow, and those borrowed funds may then be invested for the future. The mortgage payment itself is never the money invested.
Available room is not borrowing. Nothing is owed, and nothing is invested, until a separate decision is made — and the mortgage payment itself is never the money invested.
Why homeowners consider it.
Start sooner.
Begin building non-registered investments alongside the mortgage, instead of waiting until it is fully repaid.
Invest consistently.
Principal repayment may create recurring opportunities for separate investment-related borrowing — without an equivalent new contribution from ordinary cash flow.
Potential tax efficiency.
Where the applicable requirements are met, interest on qualifying investment-related borrowing may be deductible.
None of this is automatic, and the investing is funded by separate borrowing — not by the mortgage payment itself. No tax outcome, investment result or property value is guaranteed.
Open the hood.
The same idea, with its parts shown. The simple mortgage box holds two components — and the borrowing route runs through a controlled path before it reaches an investment.
One compatible readvanceable mortgage on the home holds two components: an amortizing mortgage component and a revolving borrowing component. If borrowing room is used, funds move through a controlled, traceable transaction path, and may then be directed to a non-registered investment.
One compatible readvanceable mortgage
Exact account structures and mechanics vary by lender and product.
Understand readvanceable mortgagesThe Plain Jane
Now watch it work.
The whole system, one payment at a time. It reduces principal — and that may open a separate, deliberate route.
A regular mortgage payment divides into a part that services interest and a part that reduces principal. Principal repayment may reduce the mortgage balance, which serves the home objective, and under compatible product terms may also make additional borrowing room available. Available room is not the same as borrowing: a separate decision may lead to investment-related borrowing, which carries a repayment obligation and interest, then moves through a controlled, traceable transaction path and is directed to a non-registered investment, serving the future-investment objective. The mortgage payment itself is never invested.
01 · Every month
02 · Repaying principal — two consequences
03 · The distinction the whole strategy turns on
Available credit has not been borrowed until a separate borrowing decision is made.
04 · A separate decision
05 · Moves through · 06 · Directed to
Investment values and borrowing do not move together.
The process may repeat According to the implementation plan, product terms, borrowing capacity and ongoing suitability.
Different borrowing, different treatment.
Where that deduction applies, it may reduce the after-tax cost of the investment borrowing. Whether it applies is a question of fact.
Whether interest on the investment borrowing is deductible depends on where the borrowing came from, what the borrowed funds were actually used for, and the records that connect the two — considered by your tax professional against the applicable rules and your circumstances. It is not guaranteed.
Your tax professional considers the applicable rules and your circumstances.
Clearstone does not guarantee deductibility, a refund, or any tax outcome.
It has to work over time.
Currently framed by Clearstone as 15+ years, and not suitable for everyone.
Household circumstances and borrowing costs can change while borrowing may still be outstanding under the loan terms.
Investment value can decline while some or all of the borrowing may still be outstanding.
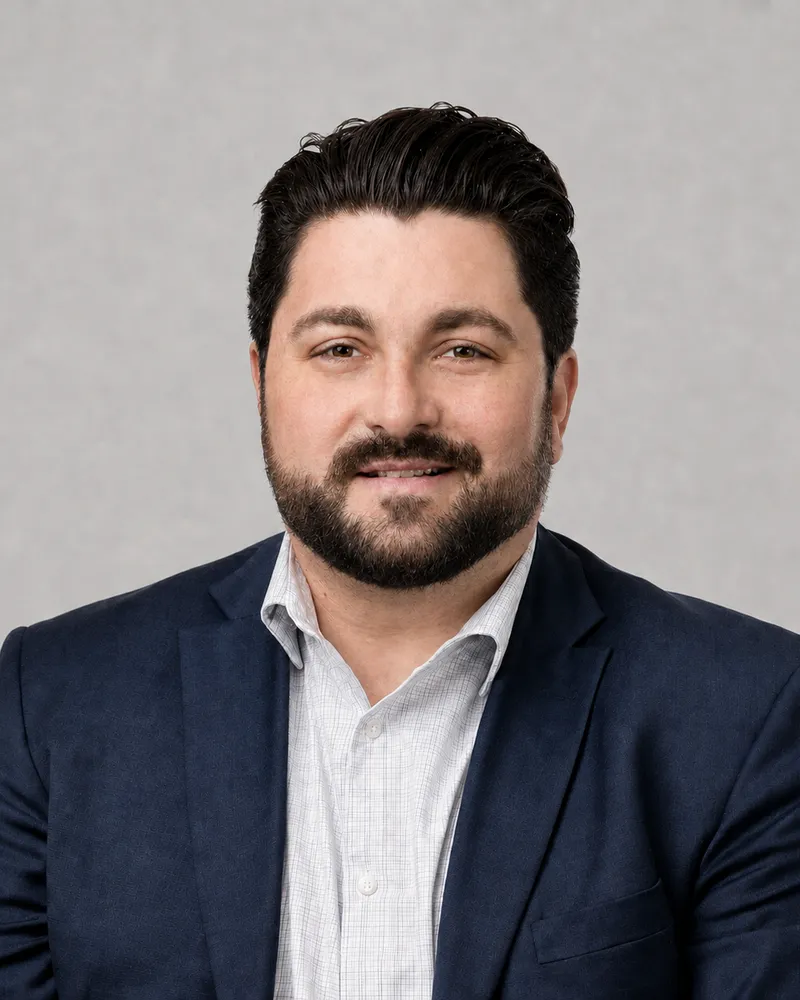
Nicholas Gaudet
Founder & CEO
The specialist accountable for Clearstone’s side of this strategy — including the judgement about whether it belongs in your picture at all.

See what the strategy could look like for you.
A person reviewing your circumstances — not a calculator returning a result. If the strategy does not fit, the assessment says so.
- 01 You share information Mortgage, cash flow, objectives.
- 02 Clearstone reviews it Against what the strategy requires.
- 03 You discuss the assessment Including the case for not proceeding.
Sharing information does not by itself establish suitability, mortgage approval, tax treatment or implementation.
The first step can simply be a conversation — not a commitment.
Start with a conversationRelated education
Smith Manoeuvre™ is a trademark used under licence through SMCG. This page is educational. Suitability, implementation and tax treatment are determined through professional review of individual circumstances.